Thanksgiving brings families together, which often makes it a natural time to raise a subject many put off. What happens if a parent can no longer make decisions, or when they pass away?
Yes, the topic can feel awkward. But a short, kind conversation when the family is already together can spare a lot of confusion later. Questions about money or inheritance are secondary—start with care and clarity and let the details come over time.
Here are some insights into how to talk about estate planning over the Thanksgiving holidays.
Quick Answer: How Do You Talk to Parents About Estate Planning at Thanksgiving?
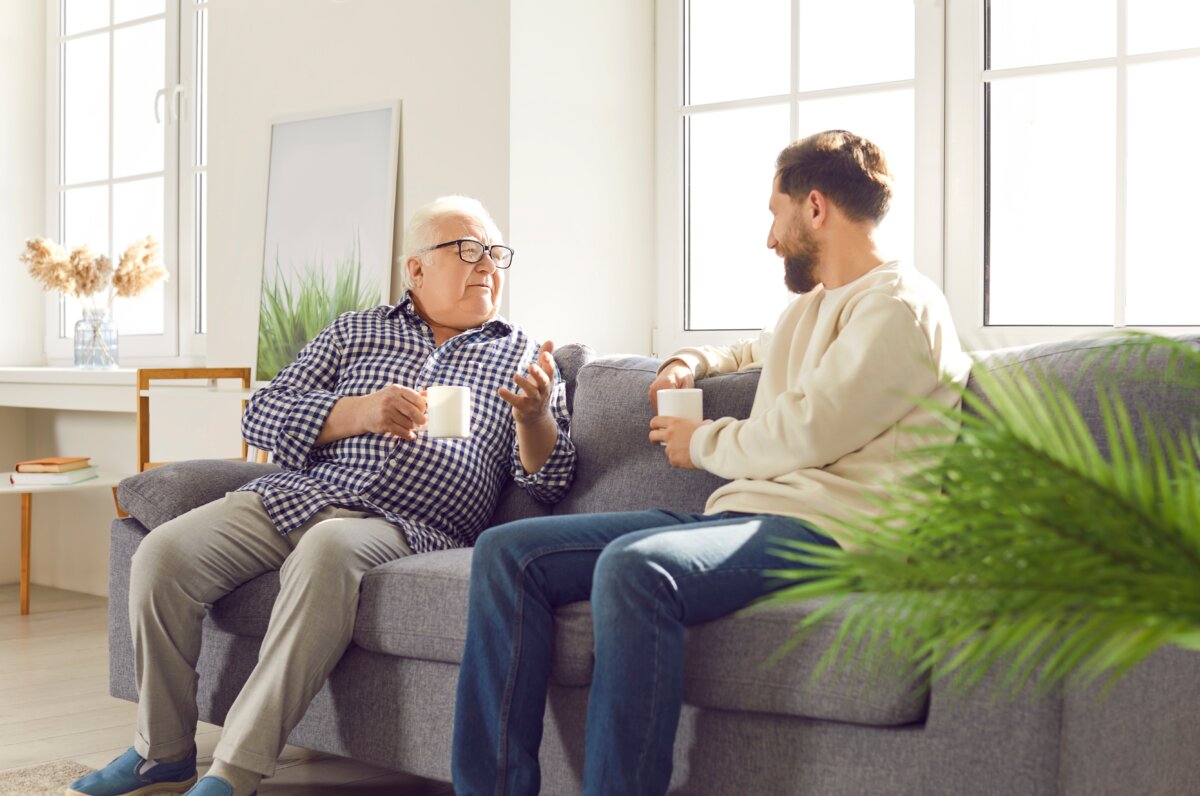
Pick a quiet moment away from the main table and consider opening the conversation with a planning- or health-focused question. This can be something like: Who will make medical decisions if they can’t? Try to learn what documents exist and where they’re kept; then plan a follow-up meeting after the holiday.
Is Thanksgiving a Good Time to Bring It Up?
It can be, but only up to a point. The holiday gives you in-person time with family members who may not live nearby, or those you may not get to see very often.
But a crowded table and a full meal aren’t an ideal scenario for a serious talk. Think of Thanksgiving as the door opener, rather than the complete conversation. Bringing up the topic during a walk, while doing dishes, or over coffee works well.
Then ask if you can sit down together another day. A neutral third-party professional, such as an estate planning attorney, can also help the follow-up talk go smoothly (if your parents are open to it).
Know the Documents Before You Start
A little background can help you ask better questions. Common documents include:
-
A will, which says who receives assets and who serves as executor.
-
A financial power of attorney, which names someone to handle money and bills.
-
A healthcare power of attorney or proxy, which names someone to make medical decisions.
-
A living will or advance directive, which records wishes about medical care near the end of life.
-
Beneficiary designations on retirement accounts and life insurance, which often override what a will says.
While many Americans have these documents ready, a surprising number do not. According to Pew Research, two-thirds of adults in their 70s (66 percent) say they’ve created a will and 64 percent have a living will or advance directive. When it comes to Americans in their 60s, those percentages drop to 46 percent and 44 percent, respectively.
Because rules surrounding wills and living wills differ by state, an estate planning or elder law attorney can confirm what applies to your parents.
Phrases You Can Adapt
These examples are just starting points, and it’s best if you can put them in your own words.
-
“We’ve been working on our own wills, and it made me wonder how you handled yours. Would you be open to talking about it sometime this weekend?”
-
“If you ever got sick and couldn’t speak for yourself, I’d want to know who you’d want making decisions. Have you named someone?”
-
“I’m not asking about amounts or who gets what. I’d just like to know where your documents are, so I can find them quickly if you ever need help.”
It also helps to frame the talk around your parents’ wishes. Naming decision-makers now means your parents choose them, rather than a court or state law choosing for them.
Hold off on asking about dollar amounts or who inherits. Those details can wait for a later talk.
Pitfalls to Avoid
-
Bringing it up in front of the whole family, since a parent may feel embarrassed or pressured to answer in front of everyone.
-
Asking about inheritance, which can make it sound like you’re only thinking about what you’ll receive.
-
Pressing for answers in one sitting, since this usually takes more than one talk.
-
Assuming your siblings already know or agree, when inviting them to the follow-up keeps anyone from feeling left out.
What If Your Parents Don’t Want to Talk?
Many parents see the topic as private, or worry they’ll be treated as if they can’t manage on their own. If your parents hesitate, back off and try again later.
Starting with healthcare wishes can feel less personal than starting with money. You can also offer to go with them to see an attorney, or leave a short checklist for them to review on their own. Some parents already have a plan and just haven’t shared it.
A Quick Note on Taxes
Most families don’t need to worry about the federal estate tax. In 2026, the federal exemption is $15 million per person. However, some states have their own estate or inheritance taxes, so a tax professional can tell you what applies.
FAQs: How to Talk to Parents About Estate Planning
When Is the Right Time to Talk to Parents About Estate Planning?
The sooner, the easier. And ideally while parents are healthy and clear-headed. Life events such as retirement, a move, a new grandchild, or a health scare can make the topic feel more natural.
What Is the Difference Between a Power of Attorney and a Healthcare Proxy?
A durable financial power of attorney names someone to handle money and bills if a parent can no longer make decisions. A healthcare proxy, sometimes called a healthcare power of attorney, lets someone make medical decisions.
What Happens if a Parent Dies Without a Will?
State law determines who receives the assets in a process called intestacy. The result may not match what your parent wanted, and the court process may take longer and cost more. Assets with named beneficiaries, such as many retirement accounts and life insurance policies, typically pass to those people regardless. Rules differ by state, so local legal advice matters.
Should Siblings Be Part of the Conversation?
Often yes, at least for the follow-up. Including everyone can reduce surprises and the feeling that one child is working behind the scenes. Your parents get to decide who joins, though, and some prefer to start one-on-one. If siblings do join, keep the focus on documents and wishes rather than fairness debates.
The Epoch Times copyright © 2026. The views and opinions expressed are those of the authors. They are meant for general informational purposes only and should not be construed or interpreted as a recommendation or solicitation. The Epoch Times does not provide investment, tax, legal, financial planning, estate planning, or any other personal finance advice. The Epoch Times holds no liability for the accuracy or timeliness of the information provided.