Commentary
China’s A-share market has faced renewed pressure since July, prompting Beijing to signal a stronger commitment to stabilizing the market.
The State Council on Nov. 6 called for improvements to the market stabilization mechanism and measures to strengthen the stock market’s underlying resilience. The announcement was significant because market support had traditionally been discussed mainly by financial regulators, not at the highest level of government.
However, state intervention and a lasting market recovery are different. Authorities may temporarily support share prices, but administrative measures cannot overcome deeper economic and institutional problems.
The weakness of China’s A-share market is not simply a matter of investor sentiment. Three structural problems help explain its persistent downward pressure: deteriorating corporate profitability, an inefficient listing and delisting system, and the valuation gap between mainland and Hong Kong-listed shares.
Weak Corporate Fundamentals and Extreme Earnings Concentration
The first problem is the deteriorating financial health of most listed companies, combined with an increasingly unequal distribution of corporate profits.
At first glance, China’s latest corporate earnings figures appear encouraging. According to the China Association of Public Companies, 5,578 listed companies had reported their third-quarter 2026 results by Oct. 31. Combined revenue reached 56.8 trillion yuan (about $8.5 trillion), up 5.9 percent year on year, while total net profit attributable to shareholders increased 8.5 percent to 5.1 trillion yuan (about $765 billion).
However, these aggregate figures mask a much weaker reality. According to an analysis cited by the Beijing-based financial news outlet Caijing, the median net profit growth rate among A-share companies was negative 9.3 percent during the first three quarters of 2026.
More importantly, profits have become increasingly concentrated among a small group of large companies, Caijing’s analysis found. The top 5 percent of listed companies—about 278—accounted for 86.08 percent of total market profits. The middle 45 percent struggled to maintain profitability, while the bottom 50 percent—nearly 2,800 companies—collectively lost about 312.5 billion yuan (about $46.9 billion).
This K-shaped divide has become increasingly pronounced. In 2021, the top 5 percent of companies accounted for approximately 65 to 70 percent of total profits. By 2024, their share had exceeded 80 percent, reaching 86.08 percent by the third quarter of 2026.
The main beneficiaries include major state-owned banks, energy companies and a small number of successful technology businesses. Meanwhile, many private manufacturers, consumer companies and smaller technology companies face weak demand, intense price competition and shrinking profit margins.
This raises a fundamental question: how can a stock market sustain a long-term bull market when the majority of its listed companies are struggling to make money?
A handful of large companies may support the headline indices, but they cannot indefinitely compensate for weak earnings across the wider corporate sector. Sustainable market growth requires broader improvements in corporate profitability and investor returns.
A Dysfunctional Market: Too Many IPOs, Too Few Delistings
The second problem is China’s failure to establish an effective system for removing unsuccessful companies from the stock market.
A healthy capital market needs continuous renewal. New businesses should be able to raise funds, while companies that can no longer operate successfully should be allowed to exit. This process directs capital toward more productive businesses and prevents the market from becoming overcrowded with financially weak companies.
The U.S. market provides a useful comparison. Between 1975 and 2012, more than 16,000 companies went public, while at least 17,000 were delisted.
Delistings occur for various reasons, including mergers, acquisitions, and bankruptcies. Market entry and exit are both essential parts of a functioning system.
China’s A-share market has historically focused much more on bringing companies onto the market than removing them. Since 1990, more than 5,800 companies have been listed, but only around 340 have been delisted, according to Chinese media East Money.
This imbalance has several consequences. The growing number of listed companies spreads available investment capital more thinly. Thousands of underperforming businesses remain listed, absorbing capital that could otherwise support more productive enterprises. Meanwhile, some newly listed companies attract heavy speculation before suffering prolonged price declines, leaving retail investors exposed to substantial losses.
The problem is particularly serious in industries where companies have similar business models and limited technological advantages. Instead of supporting innovation, the market can end up financing more businesses in already overcrowded sectors, intensifying price competition and reducing profitability.
China introduced a registration-based IPO system in 2023 and subsequently strengthened delisting requirements. Yet effective implementation remains difficult.
One major obstacle is what happens to shareholders after a company is delisted. Many delisted companies move to the lower-tier National Equities Exchange and Quotations market, commonly known as the Third Board, where trading can be extremely limited. Investors may find themselves holding shares that are technically tradable but have almost no practical liquidity.
Solving this problem requires more than restricting IPOs. China needs a more functional market for delisted shares, stronger compensation mechanisms for investors harmed by corporate fraud, and better links between delisting, bankruptcy and corporate restructuring.
These reforms, however, would challenge established corporate and local government interests. Without meaningful institutional change, the market will continue to face a fundamental imbalance: too many companies seeking capital and too few being removed when they fail to create value.
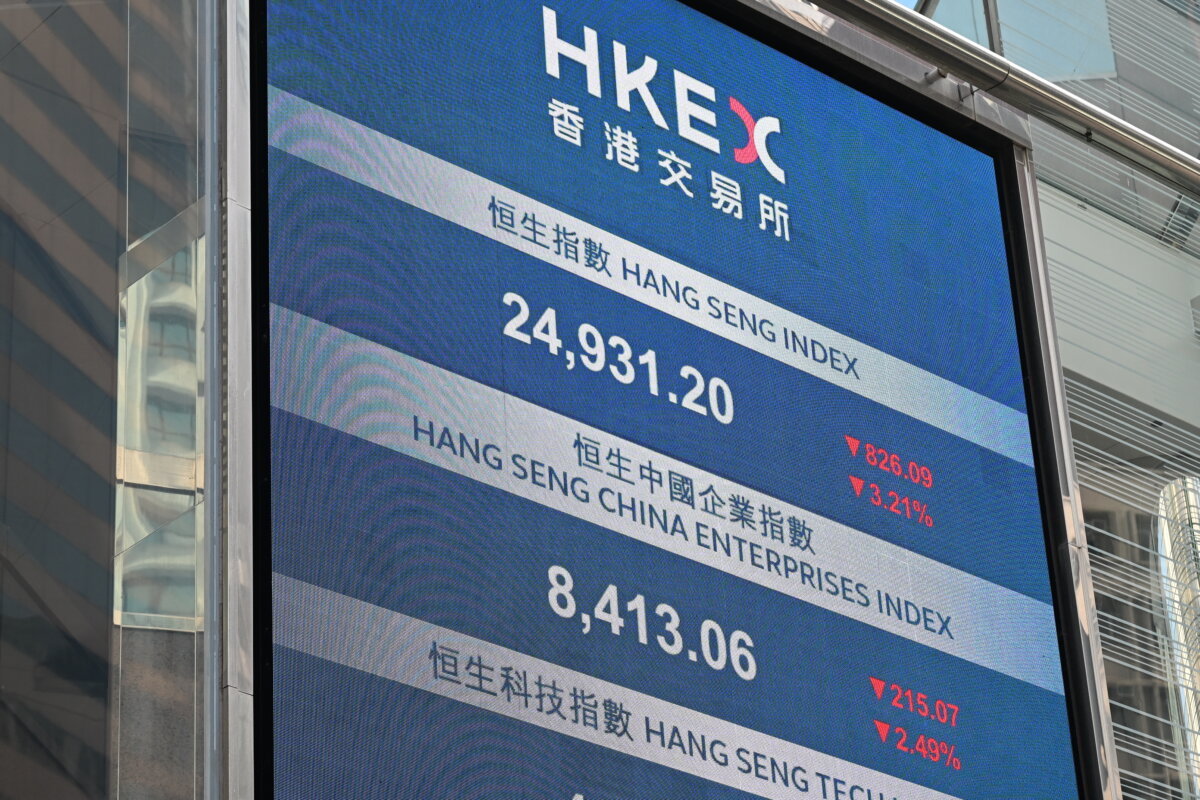
 People walk next to a screen with a stocks indicator in the Jing’an district in Shanghai on April 7, 2025. (Hector Retamal/AFP via Getty Images)
The AH-Share Premium and the Capital Control Trap
The third problem is the persistent valuation gap between mainland-listed A-shares and Hong Kong-listed H-shares of the same companies.
Many Chinese companies are listed in both markets. Although A-shares and H-shares represent ownership in the same underlying businesses, their prices can differ considerably.
The Hang Seng Stock Connect AH Premium Index measures this difference. A reading of 100 indicates equal prices, while a reading above 100 means A-shares are more expensive than their H-share counterparts.
The gap widened sharply in 2024, when the index approached 160 amid geopolitical tensions, high U.S. interest rates, and international capital outflows from Hong Kong. Although it fell to around 118 in April 2026, it widened again, reaching 134.26 on Oct. 27—its highest level in about 17 months.
This meant that mainland-listed shares were trading at an average premium of roughly 34 percent over equivalent Hong Kong-listed shares.
The premium does not directly cause A-share declines, but it reflects deeper differences between the two markets and can influence capital allocation.
Mainland China’s financial system operates under significant capital controls. Domestic investors have limited freedom to move money overseas, concentrating a large pool of savings within the domestic financial system.
Hong Kong, by contrast, is an international financial center whose valuations are more directly influenced by global interest rates, foreign investment flows, and geopolitical risks.
In recent years, concerns over U.S.–China relations and the possibility of further economic decoupling have made international investors more cautious about Chinese assets. This has contributed to lower valuations for many Hong Kong-listed Chinese companies.
The result is a persistent difference in how domestic and international investors value the same businesses. Mainland investors may be willing to pay higher prices, while international investors demand larger discounts to compensate for perceived risks.
This creates a difficult dilemma for Beijing. Authorities cannot force foreign investors to buy Hong Kong-listed Chinese shares at higher prices. Yet allowing mainland investors substantially greater freedom to purchase cheaper H-shares would require relaxing capital controls. Such a move could accelerate capital outflows, put pressure on the renminbi and threaten foreign-exchange reserves.
Consequently, policymakers have limited room to eliminate the valuation gap through direct intervention. As long as differences remain in capital mobility, investor confidence and geopolitical risk assessments, the AH-share premium is likely to remain a significant structural feature of China’s financial markets.
Conclusion: Market Stabilization Cannot Replace Structural Reform
China’s A-share market faces three interconnected problems. These problems cannot be solved simply by injecting liquidity, encouraging share buybacks, or asking financial institutions to support stock prices. Such measures may provide temporary relief, but they do not address the underlying weaknesses.
A sustainable recovery requires stronger corporate profitability, more efficient capital allocation, credible protection for minority shareholders, greater financial transparency and a more predictable regulatory environment.
Ultimately, a stock market should do more than provide companies with access to financing. It should reward businesses that create genuine economic value while protecting investors and allowing unsuccessful companies to exit.
Without meaningful progress in these areas, Beijing’s efforts to stabilize the A-share market may support prices temporarily, but they are unlikely to reverse its longer-term structural weaknesses.
Views expressed in this article are the opinions of the author and do not necessarily reflect the views of The Epoch Times.
 Friends Read Free
Copy
Facebook
Tweet