The U.S. government opened fiscal year 2027 with a record-setting $404 billion budget deficit in October, according to the Treasury Department.
Last month’s fiscal shortfall was $120 billion, or 42 percent, larger than a year ago.
Spending rose 12 percent year over year to more than $773 billion.
Medicare was the top federal outlay, totaling $170 billion. This was followed by Social Security ($143 billion), national defense ($129 billion), and net interest costs ($103 billion).
The jump in federal spending was driven in part by a $14 billion increase in Agriculture Department outlays. It also reflected a $29 billion increase in national defense outlays, according to Treasury data. Within Defense Department military programs, spending on military personnel rose by about $19 billion, operation and maintenance by about $8 billion, and procurement by about $4 billion.
Receipts, meanwhile, fell almost 9 percent from a year ago to around $369 billion.
Customs duties exceeded $19 billion, down from the $31.35 billion posted a year ago. The White House’s budget, released this past spring, projected customs receipts of $464 billion this fiscal year.
Some of October’s outlays were payments due Nov. 1 that were moved because that date fell on a weekend, according to the Treasury Department. Adjusted for those timing shifts, the deficit still rose by more than $100 billion from October 2025, according to a Congressional Budget Office estimate cited by Maya MacGuineas, president of the Committee for a Responsible Federal Budget.
MacGuineas said the federal government borrowed an average of more than $13 billion per day in October.
“We’re now in the era of $2 trillion deficits—perhaps even higher, given that October’s deficit was already one-fifth of that projected total,” MacGuineas said in a Nov. 12 statement.
“Worse so, the deficit is more than 6 percent of the economy, which is about double the level that most economists think is sustainable.”
The latest numbers underscore the difficulty of Treasury Secretary Scott Bessent’s initiative to lower the federal deficit to 3 percent of gross domestic product (GDP).
The deficit-to-GDP ratio fell to 5.8 percent in fiscal year 2025 before rising again to around 6.2 percent in fiscal 2026 as the government posted a $2 trillion shortfall.
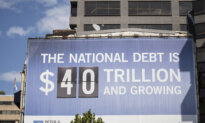
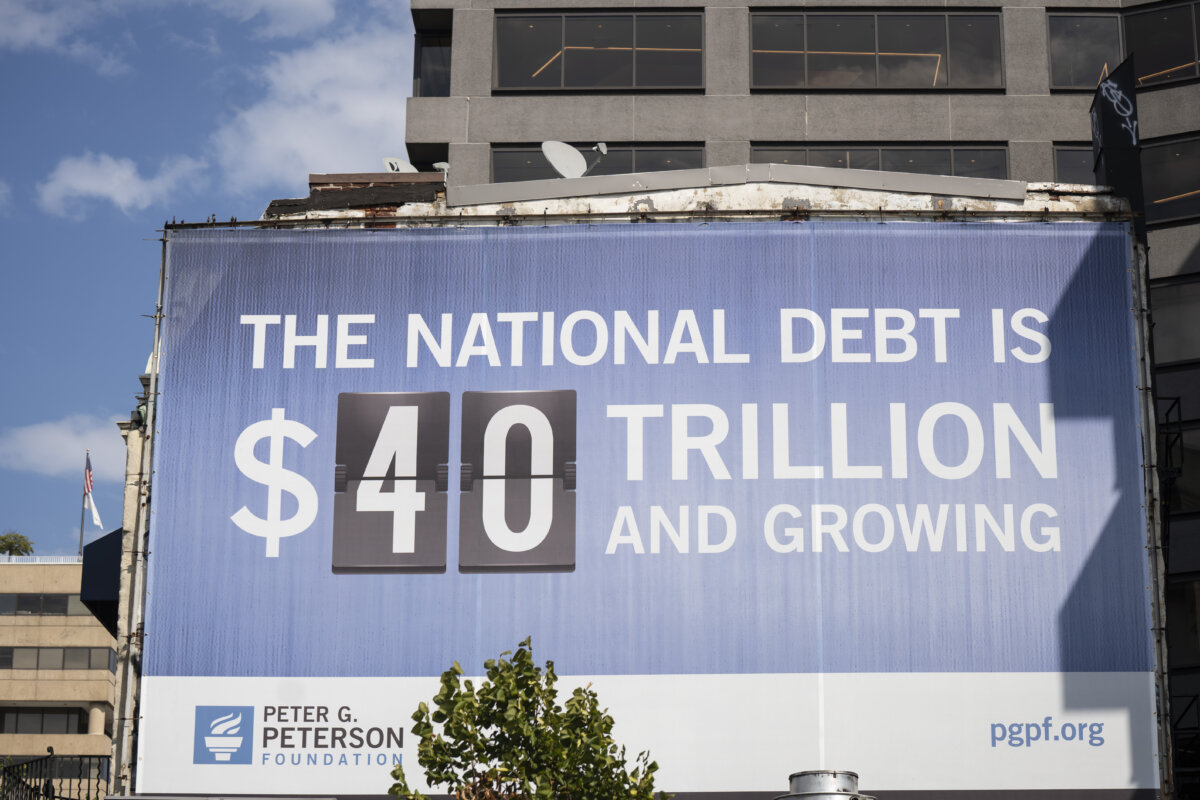
The United States is weeks away from reaching the $41 trillion national debt milestone.
As of Nov. 10, the Treasury’s Debt-to-the-Penny dashboard shows total public debt standing at $40.58 trillion.
Debt Ceiling Showdown on the Horizon
The federal government is close to hitting the debt ceiling, currently set at $41.1 trillion and established under last year’s One Big Beautiful Bill Act.
The Bipartisan Policy Center estimated in June that the government would most likely reach the debt limit between late winter and mid-summer of 2027.
The Treasury will then employ extraordinary measures—suspending Government Securities Investment Fund reinvestments, pausing new debt issuance, and halting Exchange Stabilization Fund reinvestments—to keep paying the government’s bills. The center estimated that those measures would last another six to nine months. After this period, the X-date—the date the government defaults without congressional action—is reached.
Repeated debt-ceiling standoffs have contributed to downgrades by the leading credit agencies—Fitch, Moody’s, and S&P—over the years.
To avoid these routine standoffs, some officials, including President Donald Trump and Sen. Elizabeth Warren (D-Mass.), have proposed repealing the debt ceiling.
“I would support that entirely,” Trump told NBC News in December 2024.
“The Democrats have said they want to get rid of it. If they want to get rid of it, I would lead the charge.”
Others have suggested letting the United States default. But this would have dramatic economic consequences, said Andrew Lautz, senior director of federal policy at the Tax Foundation.
“Default would be an even greater mistake than repealing the debt limit. A default could lead to a permanent increase in U.S. borrowing costs,” Lautz wrote in a Nov. 3 blog post.
This could raise borrowing costs and widen the gap between spending and revenues, eventually causing significant tax increases. A default could also delay Social Security and military payments and spook global financial markets.
“A middle path might be bipartisan debt limit reform that takes the worst of the brinksmanship off the table while establishing more regular intervals for Congress to debate and enact fiscal reforms,” Lautz added.
 Friends Read Free
Copy
Facebook
Tweet